Should You Sell Your Huntsville Home Before Buying?
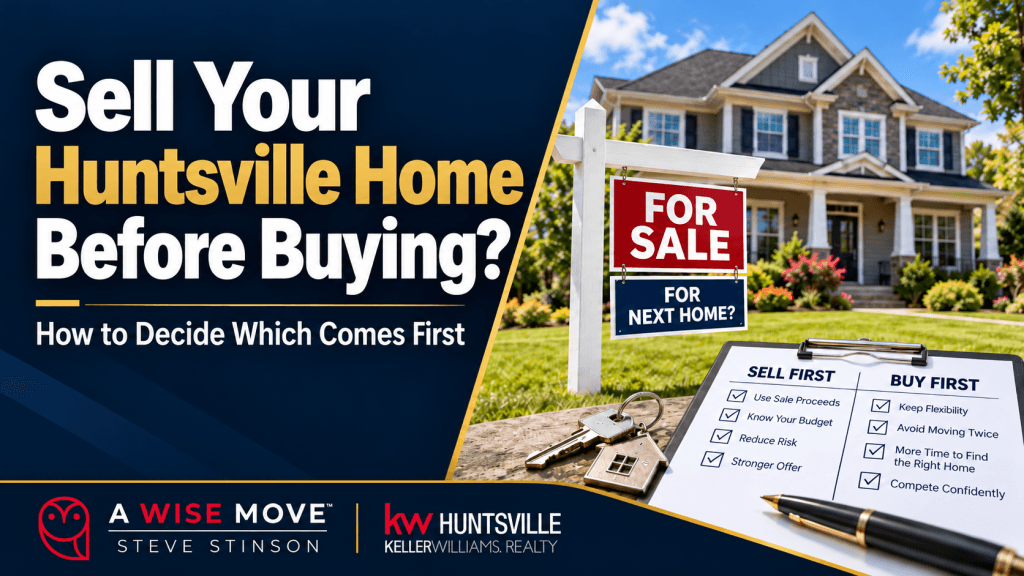
Selling your Huntsville home before buying is not automatically the right choice. The deciding factors are your finances, whether you need proceeds from the existing home to purchase the next one, and whether you can comfortably carry two mortgages. Sell first for greater financial certainty, or consider buying first when your cash and lender approval support it.
Since 2005, I have approached this decision around the homeowner’s individual financial circumstances, not a one-size-fits-all rule. The goal is to protect your equity and avoid letting a rushed move force a pricing decision you would not otherwise make.
Which option fits your situation?
| Approach | Main benefit | Main exposure | Best first step |
| Sell first | Know actual proceeds | Possible temporary housing | Plan occupancy |
| Buy first | Secure replacement home | Two-home carrying costs | Lender review and reserves |
| Sale contingency | Purchase tied to your sale | Seller may reject the condition | Negotiate contract deadlines |
Should you sell your Huntsville home before buying?
The main reason to sell first is financial. If you need equity from your current home to make the down payment or qualify for your next purchase, selling first gives you access to those proceeds after closing and reduces uncertainty. It can also be the better option if making two mortgage payments would strain your budget.
That certainty comes with a tradeoff. You may sell before finding the right replacement. A longer closing, a carefully negotiated post-closing occupancy agreement, or a short-term rental can help, but none is automatic. A buyer has to agree, and any occupancy terms must fit the contract, insurance, and financing requirements.
I start with expected net proceeds rather than the list price. Mortgage payoff, selling expenses, negotiated concessions, and other charges affect how much cash you actually receive. From there, the lender can help determine whether selling first is necessary or simply preferable.
When does buying first make more sense?
Buying first can make sense when you have the cash to purchase the replacement home and can comfortably carry the old and new mortgages if your current house takes longer to sell. It may let you secure the home you want and avoid moving twice. But qualifying for two payments is not the same thing as being comfortable making them.
Ask the lender to review your situation before making an offer. Review the estimated total monthly payment, cash needed to close, reserves, and how the existing mortgage will be treated. The CFPB Loan Estimate explainer is a useful reference for understanding payment and cash-to-close figures.
In my experience, the main difficulty in buying before selling is that the original home may not sell within its expected time on market. That is why I spend substantial time with clients on preparation and pricing before they move. Once a homeowner has moved into the new property, the old one needs to be positioned to attract buyers, not left sitting with a price that depends on what the owner needs.
How much could carrying two homes cost?
Use a stress test rather than a best-case estimate. Add the full monthly carrying cost of your current home to the complete monthly cost of the new one. Include principal, interest, taxes, insurance, HOA dues where applicable, utilities, lawn care, and maintenance that continues while the original home is for sale.
For example, if the current home costs $2,000 monthly to carry and the replacement costs $2,700, the combined cost would be $4,700 per month before moving costs and unexpected repairs. Three months of overlap would mean $14,100 in combined housing costs. This is a hypothetical illustration, not a Madison County market average. Some of that cost would exist regardless of timing; the decision is whether the overlap is manageable.
The next question is whether your reserves still work if the original house takes longer to sell or needs a price reduction. If that would put you in a difficult position, do not treat lender approval alone as a reason to buy first.
How long might your Huntsville home take to sell?
Market averages are planning context, not a forecast for your home. According to the Huntsville Area Association of REALTORS®, September 2026 single-family homes in Madison County recorded 41 days on market until sale and 4.1 months of supply. HAAR characterized that overall supply as a balanced market with more breathing room for buyers. These figures do not establish a buyer’s market in every neighborhood or price range.
A separate Federal Reserve Bank of St. Louis series, sourced from Realtor.com, reported a 79-day median time on market for the larger Huntsville metropolitan area in September 2026. This is a different measure and geography from HAAR’s Madison County figure, so the two should not be averaged or treated as interchangeable.
A home’s pricing, condition, competition, and location matter more than the market average alone. For a fuller breakdown, see how long it takes to sell a house in Huntsville. If you are still weighing the timing of the move itself, read whether to sell now or wait.
Can a home-sale contingency protect you?
A home-sale contingency makes your purchase depend on selling your existing house under terms specified in the written offer. Historically, I found it difficult to get sellers to accept these contingencies. With buyers having more choices in many parts of our market, I am seeing more room to discuss them. The seller still has to agree, and acceptance depends on the specific property and offer.
A contingency can be more attractive when your existing home is already under contract, especially after its inspection period has passed. That does not eliminate the risk of the sale falling through, but it may give the seller more confidence than an offer contingent on a home that has not been listed. The contract must clearly spell out deadlines, notices, and any kick-out rights.
What if your two closings do not line up?
Closings do not need to happen on the same day. If your new purchase relies on cash from your old sale, coordination matters because funding, title work, lender requirements, or another party’s delay can upset the schedule. One alternative I discuss is arranging for the buyer of your existing home to let you remain there after closing.
When the buyer agrees, a written post-closing occupancy or extended-stay agreement may let you close on your current home, release its equity, and remain there for a negotiated period while you find and move into the next property. In some cases, that can eliminate an intermediate move altogether. A stay of a couple of months is possible only when the particular buyer, lender, insurer, and written terms permit it. Address rent or fees, deposits, move-out date, utilities, insurance, damage, and late departure before signing.
For the full coordination process, read buying and selling at the same time. The stages between contract and closing are explained in what happens after an offer is accepted.
What should you do before putting your house on the market?
Before listing, I want three things clear: what your current house is realistically worth, whether you can carry a second mortgage, and how much cash you need from the sale. Then we work on the preparation and price that will give the old home its best chance of selling promptly after you move, if buying first is the plan.
- Calculate likely proceeds after payoff and selling expenses, not just the hoped-for sale price.
- Ask your lender to model the purchase with and without the current mortgage.
- Compare the cost of a temporary move with several months of overlapping housing expenses.
- Prepare the current home before making promises tied to its sale. Review what to fix before selling.
- Put all contingency and occupancy terms in writing and have the right professionals review them.
My strongest caution for someone buying first is simple: do not count on your old home selling quickly unless its condition, presentation, and asking price justify that expectation. A strong preparation and pricing plan does not guarantee a quick sale, but it reduces avoidable obstacles.
Have a question about the Huntsville housing market?
Get straight, local answers about selling, buying, relocating, investing, or building in the Huntsville area. No pressure.
Since 2005 · 500+ Families Served · 250+ Five-Star Reviews · BBB A+ Rated
Frequently Asked Questions
Is it safer to sell before buying?
It is often financially safer if you need the equity to buy the next home or cannot comfortably carry two mortgages. If your cash reserves and lending position comfortably support both properties, buying first may be reasonable.
Can I qualify for a new mortgage before my old house sells?
Possibly. Qualification depends on your income, debts, assets, loan program, and lender underwriting. Ask for an individualized review before making a purchase offer.
Will a sale contingency hurt my offer?
It can, but local conditions and how far along your existing sale is make a difference. A seller may view a contingency more favorably if your current home is already under contract and its inspection period has passed.
Can I stay in my home after closing?
Yes, if the buyer agrees to a written post-closing occupancy arrangement and the relevant financing and insurance requirements allow it. That may free up sale proceeds while avoiding an intermediate move.
What if the new home appraises below the purchase price?
The parties may renegotiate, you may need additional cash, or contractual protections may offer another outcome. Review the appraisal provisions with your closing professionals before waiving protections.
A Wise Move starts with a plan
If you are planning to move, start with the financial question: do you need your current home’s equity, and can you comfortably support two mortgage payments if its sale takes longer than expected? From there, I can help you evaluate the property’s likely selling timeline, the preparation and pricing it needs, and whether a contingency or negotiated extended stay could make the move easier. Schedule a strategy conversation before you commit to the next purchase.
About Steve Stinson
Steve Stinson is a REALTOR® and Broker Associate with Keller Williams Realty in Huntsville, Alabama. He has served sellers and buyers across Madison County since 2005.
Steve’s practice centers on four areas: listing and selling homes, relocation to the Huntsville market, investment property, and new construction. He also handles expired listings and downsizing. He works with clients in Huntsville, Madison, Hampton Cove, Owens Cross Roads, and surrounding Madison County communities, and helps owners weigh open-market sales against local cash-buyer offers so they can compare speed, price, and terms with confidence.
He has served 500+ families making A Wise Move and earned 250+ verified 5-Star reviews, most of them on Google. Steve is a Best of Zillow award recipient and consistently ranks in the top 5% of the local MLS as a listing agent. A Madison County resident since 1980, he brings deep local knowledge and pricing strategy to every move.
Equal Housing Opportunity. This content is general information only. It is not legal, tax, or financial advice. Confirm your specific costs, tax obligations, and transaction details with your closing attorney, tax advisor, lender, or escrow officer. Broker compensation is fully negotiable and not set by law; no standard or typical rate exists.
Sources
Huntsville Area Association of REALTORS®, October 2026 market update: September 2026 Madison County days on market and months supply. https://haar.realtor/category/stats/
Federal Reserve Bank of St. Louis, Realtor.com via FRED, September 2026: Huntsville metropolitan area median days on market. https://fred.stlouisfed.org/series/MEDDAYONMAR26620
Consumer Financial Protection Bureau: Estimated housing payments and cash required to close. https://www.consumerfinance.gov/owning-a-home/loan-estimate/